A realistic retirement travel budget can help you see more of the world without turning every trip into a source of financial stress. The goal is not to make every vacation as cheap as possible. It is to decide what deserves your money, identify the costs that add little value, and create a travel plan that can continue for years.
Travel remains a priority for many adults over 50. According to the AARP 2026 Travel Trends study, nearly two-thirds of adults age 50 and older planned to travel in 2026, despite concerns about prices and economic uncertainty.
That combination is important. People still want to travel, but they are paying closer attention to value.
A good retirement travel budget should make room for comfort, health, flexibility, meaningful experiences, and the occasional splurge. It should also protect you from spending too much on fees, rushed decisions, and conveniences you do not actually need.
Quick Answer: How Can Retirees Travel More for Less?
Retirees can travel more affordably by setting an annual travel budget, choosing off-peak dates, comparing several destinations, using rewards carefully, asking about age-based discounts, staying longer in fewer places, and reviewing medical coverage before leaving home.
The most effective strategy is not one dramatic discount. It is combining several smaller decisions that reduce the total cost without making the trip uncomfortable.
Why Is a Retirement Travel Budget Different?
Travel planning changes when you are no longer limited to the same vacation calendar you followed while working.
You may have more control over your dates. You may be able to travel on a Tuesday instead of a Friday, stay for three weeks instead of rushing through seven days, or visit a destination just before or after its busiest season.
At the same time, your priorities may have changed.
You might care more about:
- convenient flight schedules;
- fewer connections;
- comfortable beds;
- walkable neighborhoods;
- reliable transportation;
- medical coverage;
- manageable luggage;
- slower itineraries;
- flexible cancellation terms;
- extra rest between activities.
These choices may cost more in one part of the trip while saving money elsewhere. A centrally located hotel may be more expensive per night, for example, but it can reduce transportation costs and make the experience less tiring.
That is why a retirement travel budget should not be built only around the lowest advertised price. It should reflect the total cost and the kind of experience you want to have.
1. How Much Should You Set Aside for Retirement Travel?
Begin with an annual number, not with a destination.
When people start with a dream trip, it is easy to build a plan around emotion and only calculate the final cost later. Starting with the amount you can comfortably spend creates a useful boundary before you compare flights, hotels, cruises, or tours.
Your annual travel budget can include:
- transportation;
- accommodations;
- meals;
- insurance;
- local transportation;
- attractions and tours;
- luggage fees;
- tips;
- medications and health needs;
- pet or home care;
- mobile data;
- passport and visa expenses;
- a contingency reserve.
Do not use every dollar for the visible parts of the trip. Keep approximately 10 to 15 percent of the planned amount available for changes, emergencies, price increases, or something meaningful you discover along the way.
If your annual travel budget is $6,000, for example, you could divide it into:
- one larger trip costing $3,500;
- two shorter trips costing $1,000 each;
- a $500 reserve for unexpected expenses.
Another option would be three domestic trips of approximately $1,500, with the remainder kept for flexibility.
The right division depends on what matters to you. Some people prefer one important international trip. Others would rather travel more often and stay closer to home.
A budget becomes more useful when it reflects your real travel personality.
2. Can Traveling During Shoulder Season Reduce Costs?
Traveling just before or after the busiest period can reduce airfare and accommodation costs while offering a calmer experience.
This period is often called shoulder season. Its exact dates depend on the destination.
In Europe, late spring and early fall can offer pleasant conditions without the peak summer crowds. Beach destinations may become more affordable after school vacations end. National parks can feel different in late spring or early autumn than during the busiest summer weeks.
Shoulder-season travel can offer:
- lower hotel rates;
- more flight options;
- shorter lines;
- less crowded attractions;
- easier restaurant reservations;
- cooler temperatures;
- a slower pace.
There are tradeoffs. Some seasonal businesses may be closed, daylight hours may be shorter, and the weather can be less predictable.
Before booking, check:
- typical temperatures and rainfall;
- public transportation schedules;
- seasonal hotel or restaurant closures;
- local holidays and festivals;
- accessibility of the attractions you want to visit.
A lower price is not valuable if the main reason for your trip is unavailable. The goal is to travel outside the most expensive weeks while still having the experience you want.
3. Why Should You Compare Experiences Instead of Destinations?
Many travelers decide they want to visit a famous destination without identifying what they want from it.
Instead of beginning with a city or country, begin with the experience.
Do you want:
- historic streets and museums?
- warm weather near the water?
- mountain scenery?
- good food and local markets?
- a quiet place to rest?
- a train journey?
- time with family?
- cultural events?
- a walkable small town?
Once the experience is clear, compare several places that can provide it.
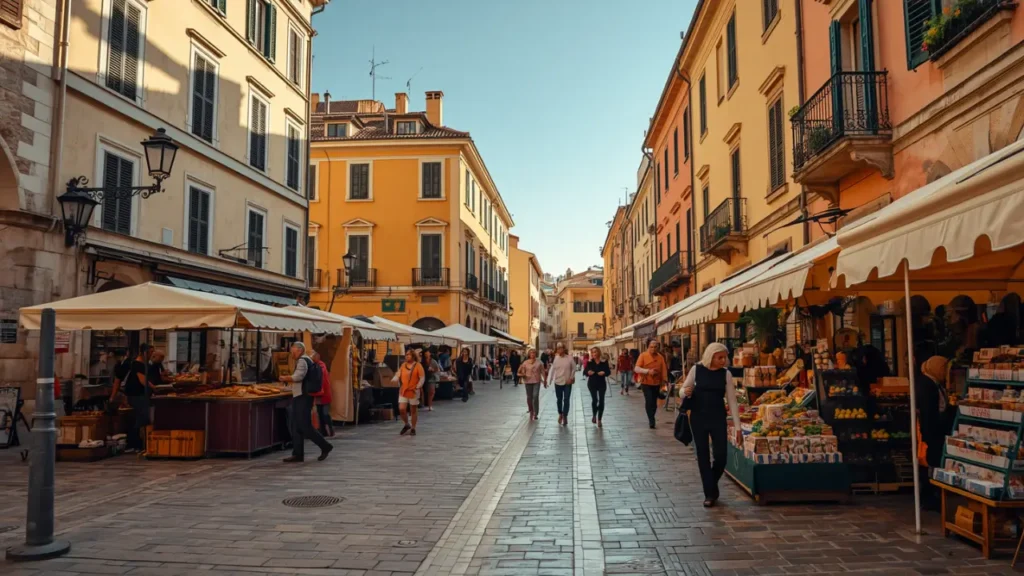
If you want a European town with historic architecture and good food, the most famous city may not be the only option. A smaller city nearby may offer lower prices, fewer crowds, and a more relaxed pace.
The same principle applies within the United States. A popular coastal destination may have alternatives with a similar atmosphere and more affordable accommodations.
Choosing a less obvious destination can reduce costs without reducing the quality of the trip. It may even create a more personal experience because you are not moving through the same overcrowded itinerary as everyone else.
This does not mean you should avoid iconic places. It means you should understand why you want to go there and whether another destination could provide what you are truly looking for.
4. How Can Flexible Transportation Choices Save Money?
Transportation is often one of the largest parts of a retirement travel budget. Flexibility can make a significant difference.
Compare:
- nearby departure airports;
- direct and connecting flights;
- train and air travel;
- driving and flying;
- round-trip and separate one-way tickets;
- different days of the week;
- morning, afternoon, and evening departures.
However, do not automatically choose the cheapest option.
A low-cost flight with two connections, a long overnight layover, expensive baggage fees, and an airport far from the city may cost more overall than a slightly more expensive direct flight.
Consider the full journey:
- How will you reach the airport?
- Will you need a hotel before an early departure?
- Are checked bags included?
- How much will transportation from the arrival airport cost?
- Will the schedule leave you exhausted for the first day?
- What happens if one connection is delayed?
For U.S. train travel, Amtrak currently advertises a 10 percent senior discount on most trains, subject to its eligibility rules and restrictions. Always confirm current terms before booking.
When buying airfare directly from an airline, remember that the U.S. Department of Transportation requires covered airlines to allow a 24-hour hold or penalty-free cancellation for qualifying reservations made at least seven days before departure. This protection may not apply in the same way when booking through a third-party travel agency, so read the conditions carefully.
[NÃO PUBLICAR: inserir link interno no trecho abaixo.]
If a national park trip is part of your plan, review these practical [national park rules before you travel].
5. Are Senior Travel Discounts Worth Asking About?
Yes, but only when the discounted price is actually the best available price.
Age-based discounts may be available for:
- trains;
- public transportation;
- museums;
- attractions;
- hotels;
- rental cars;
- tours;
- national and state parks;
- local cultural programs.
Eligibility ages vary. One company may begin discounts at 60, another at 62 or 65. Some discounts must be requested during booking and cannot be added later.
U.S. citizens and permanent residents age 62 and older may qualify for the National Park Service Senior Pass. The official pass information should be checked before purchasing because prices, eligibility requirements, and covered fees can change.
A discount label does not always guarantee the lowest price. A hotel’s public promotion, loyalty-member price, prepaid rate, or package may be less expensive than its senior rate.
Compare the final totals, including:
- taxes;
- resort fees;
- parking;
- breakfast;
- baggage;
- cancellation conditions;
- required memberships.
Ask about the discount, but compare it with every other available offer.
6. How Can You Use Travel Rewards Without Overspending?
Points and miles can lower travel costs, but only when they support your existing spending rather than encouraging you to spend more.
Before applying for a travel credit card or moving points between programs, ask:
- Is there an annual fee?
- Will I use the included benefits?
- Are there foreign transaction fees?
- Do the points expire?
- Can redemption values change?
- Are there blackout dates or limited seats?
- Will I pay the balance in full?
- Could I earn a simpler cash-back reward instead?
The Consumer Financial Protection Bureau advises consumers to compare credit card fees with the actual value of the rewards. A card with airport lounge access may sound appealing, but the benefit has little value if your airport or airline is not included.
Keep your rewards strategy simple.
One airline program, one hotel program, and one flexible rewards account may be easier to manage than several small balances scattered across different companies.
Also compare a points redemption with the cash price. Using 40,000 points for an inexpensive ticket may offer poor value, especially if you are also required to pay taxes and fees.
Points are a tool, not free money. Interest charges, annual fees, and unnecessary purchases can quickly erase the value of a reward.
7. Can Staying Longer in Fewer Places Cost Less?
Slow travel can be both more affordable and more comfortable.
Moving between several destinations creates repeated costs:
- train or airline tickets;
- airport transportation;
- baggage handling;
- check-in and cleaning fees;
- convenience meals;
- lost time;
- higher stress.
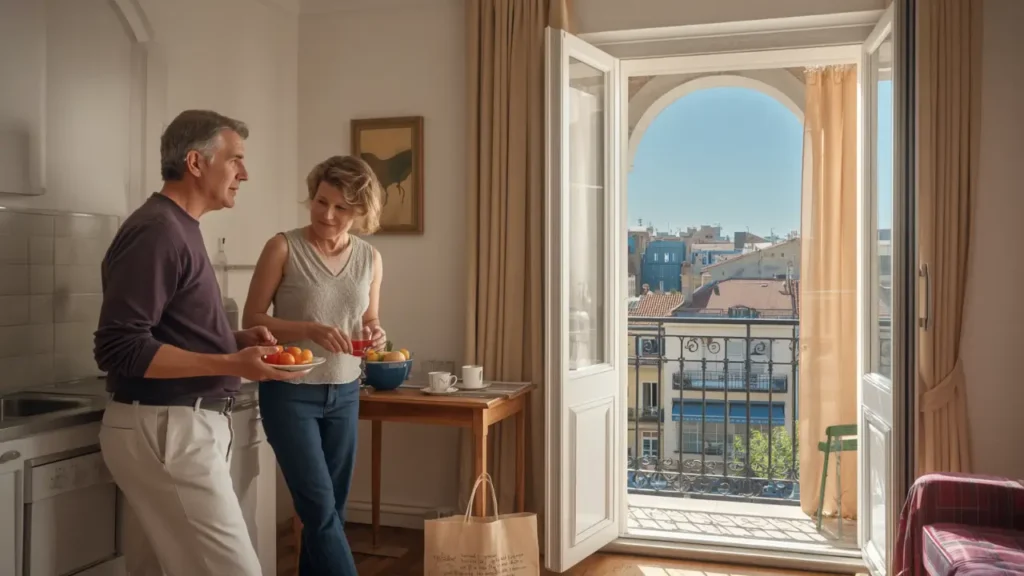
Staying longer in one place may give you access to weekly or monthly accommodation rates. An apartment or room with a small kitchen can also reduce the need to eat every meal in a restaurant.
This does not mean cooking throughout your vacation. It may simply mean having breakfast at the apartment, keeping fruit and drinks available, and saving restaurant spending for meals that feel special.
A longer stay also gives you time to:
- use local public transportation;
- explore beyond the main attractions;
- shop at neighborhood markets;
- rest without feeling guilty;
- take day trips;
- return to places you enjoy;
- adjust plans according to the weather.
When comparing accommodations, calculate the complete cost.
A cheaper property far from the center may require daily taxis or long transfers. A slightly more expensive apartment in a walkable neighborhood could provide better value.
Comfort and location are not luxuries when they reduce exhaustion and transportation expenses.
8. Which Hidden Travel Costs Should Be Included?
A trip can exceed its budget even when the flight and hotel were carefully planned. The problem is often the collection of smaller costs that were never included.
Common hidden expenses include:
- checked and carry-on baggage fees;
- seat selection;
- hotel resort or destination fees;
- parking;
- rental-car insurance and fuel;
- tolls;
- airport transfers;
- mobile roaming;
- foreign transaction fees;
- tips;
- local taxes;
- currency exchange;
- laundry;
- medication replacement;
- pet care;
- house sitting;
- meals during delays;
- early check-in or late checkout.
Create a “before and after” section in your retirement travel budget.
Before the trip, you may need to pay for passports, luggage, clothing, vaccinations, pet care, or transportation to the airport.
After the trip, there may be credit card charges, currency adjustments, airport parking, or expenses from the journey home.
A practical way to estimate these costs is to review the total from your most recent trip. Look beyond the original reservation and examine everything you spent from the moment you left home until the day you returned.
That real number is more useful than an idealized estimate.
9. When Is Travel Insurance Worth the Cost?
Travel insurance should be evaluated according to the amount you could lose and the coverage you already have.
Before purchasing a policy, review:
- trip cancellation limits;
- trip interruption coverage;
- emergency medical expenses;
- emergency evacuation;
- preexisting-condition requirements;
- age-related restrictions;
- covered reasons for cancellation;
- exclusions;
- deductibles;
- reimbursement procedures.
Do not assume that every policy includes meaningful medical coverage.
This is especially important for international travel. Medicare states that it generally provides limited medical coverage outside the United States. Some Medigap policies may include foreign emergency coverage, and some Medicare Advantage plans may offer emergency or urgently needed services abroad, but coverage varies.
Check your specific plan before leaving the country. Do not rely on a general statement found online or on what another traveler’s policy covered.
Travel insurance may be more valuable when:
- the trip has large nonrefundable costs;
- you are traveling internationally;
- your health insurance has limited destination coverage;
- emergency transportation would be expensive;
- weather could disrupt the itinerary;
- you booked far in advance;
- a cruise or organized tour has strict cancellation terms.
It may offer less value when most reservations are refundable and the financial loss would be manageable.
Insurance is not automatically a good or bad purchase. It is a transfer of risk. Compare the premium with the amount you could reasonably lose.
10. Where Should You Save and Where Should You Spend More?
The strongest travel budget is not the one with the lowest total. It is the one that reflects your priorities.
You might save on:
- traveling outside peak season;
- breakfast and simple lunches;
- unnecessary souvenirs;
- oversized luggage;
- expensive airport transfers;
- attractions that do not genuinely interest you;
- changing cities every two days;
- premium rooms when you will barely use them.
You might spend more on:
- a direct flight;
- a safer or more convenient neighborhood;
- a comfortable bed;
- reliable travel insurance;
- reserved seating;
- transportation that reduces physical strain;
- a meaningful experience;
- an extra night that makes the itinerary less rushed.
Choose two or three comfort priorities before booking.
For one traveler, that might mean a direct flight and a central hotel. For another, it could mean premium train seats and a private guide for one important day.
Spending intentionally is different from spending impulsively.
When you know what improves your trip, you can reduce costs in areas that matter less without feeling deprived.
What Could a Retirement Travel Budget Look Like?
Here is a simple example for a seven-night domestic trip for two people. Actual prices vary significantly by destination, season, departure city, and personal choices.
| Expense | Planned Amount |
| Transportation | $900 |
| Accommodation | $1,400 |
| Meals | $700 |
| Local transportation | $250 |
| Attractions and activities | $350 |
| Insurance | $150 |
| Pet or home care | $200 |
| Contingency reserve | $300 |
| Estimated total | $4,250 |
The purpose of this example is not to establish the correct amount. It is to show that the flight and hotel are only part of the total.
Your own categories may look different. A road trip could require more for fuel and parking. An international trip may need more for insurance, mobile data, and airport transportation. A family visit may reduce accommodation costs but increase spending on meals and shared activities.
How Can You Keep the Budget on Track During the Trip?
You do not need to record every cup of coffee, but you should know whether the trip is following the general plan.
A simple system is to divide spending into three groups:
- Fixed costs already paid
- Daily flexible spending
- Emergency reserve
If you have $1,000 available for meals, transportation, and activities over ten days, your average flexible amount is $100 per day.
Some days will cost more and others less. The average gives you a reference without turning the trip into an accounting exercise.
Check spending every few days rather than waiting until you return home. If restaurant costs are higher than expected, you can adjust upcoming meals or choose a free activity without affecting the entire vacation.
The purpose of tracking is awareness, not guilt.
What Should You Do Before an International Trip?
For international travel, add a practical preparation checklist to your budget.
Confirm:
- passport validity;
- visa or electronic authorization requirements;
- health insurance coverage;
- prescription medication rules;
- foreign transaction fees;
- mobile phone options;
- emergency contacts;
- local transportation;
- accessibility needs;
- cancellation policies.
U.S. citizens can also review destination-specific information and enroll in the free Smart Traveler Enrollment Program to receive alerts from the nearest U.S. embassy or consulate.
If travel represents a new beginning after a major transition, read The First Trip After a Life Change: 10 Meaningful Ways to Travel Again
A Travel Budget Should Create Possibility
A retirement travel budget is not meant to make life smaller. It is meant to help travel remain possible.
When you know what you can spend, you can make decisions with more confidence. You can compare destinations without guessing, choose comfort without feeling irresponsible, and say no to expenses that do not improve the experience.
The real goal is not to collect the greatest number of destinations.
It is to create trips that fit your health, finances, curiosity, and current season of life.
Maybe that means one international journey every two years. Maybe it means several road trips, train journeys, family visits, or quiet weeks near the ocean. Maybe it means traveling more slowly and staying long enough to feel part of a place.
There is no single correct retirement travel budget.
There is only the budget that helps you continue exploring without sacrificing the stability that makes those journeys possible.
Gui Perine
Gui Perine is the creator of Your Life in Full Bloom, a lifestyle website for women who want to live with more intention, beauty, and freedom after 50.
Through thoughtful articles on home, travel, reinvention, and everyday choices, she explores what it means to build a fuller life in a new season — one that feels calmer, more personal, and more aligned with who you are becoming.
Her work is inspired by real-life transitions, the desire for independence, and the belief that life after 50 can be a time of clarity, possibility, and renewal.